| Metric | Value |
| Market Cap (₹ Cr) | ₹ 11,13,174.00 |
| ROCE (%) | 6.92% |
| Current Ratio | 2.35% |
| ROE (%) | 14% |
| Return on Assets (%) | 1.8% |
| Debt to Equity | 6.28 |
| Branches | 9694 |
| NIM (%) | 3.26% |
| Cost to Income Ratio (%) | 39.2% |
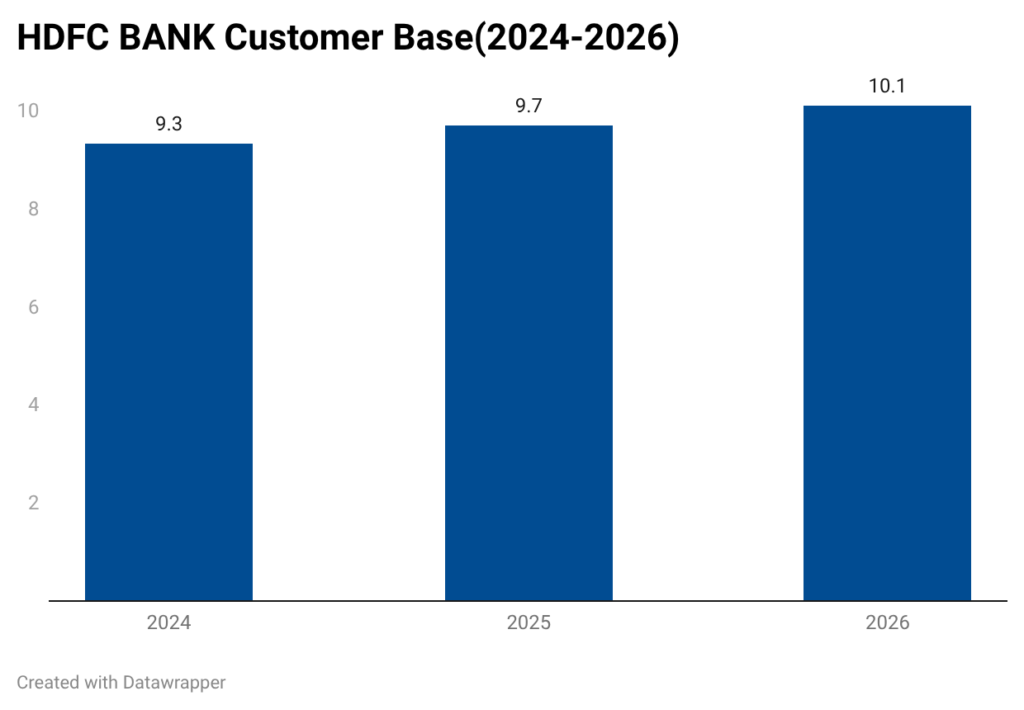
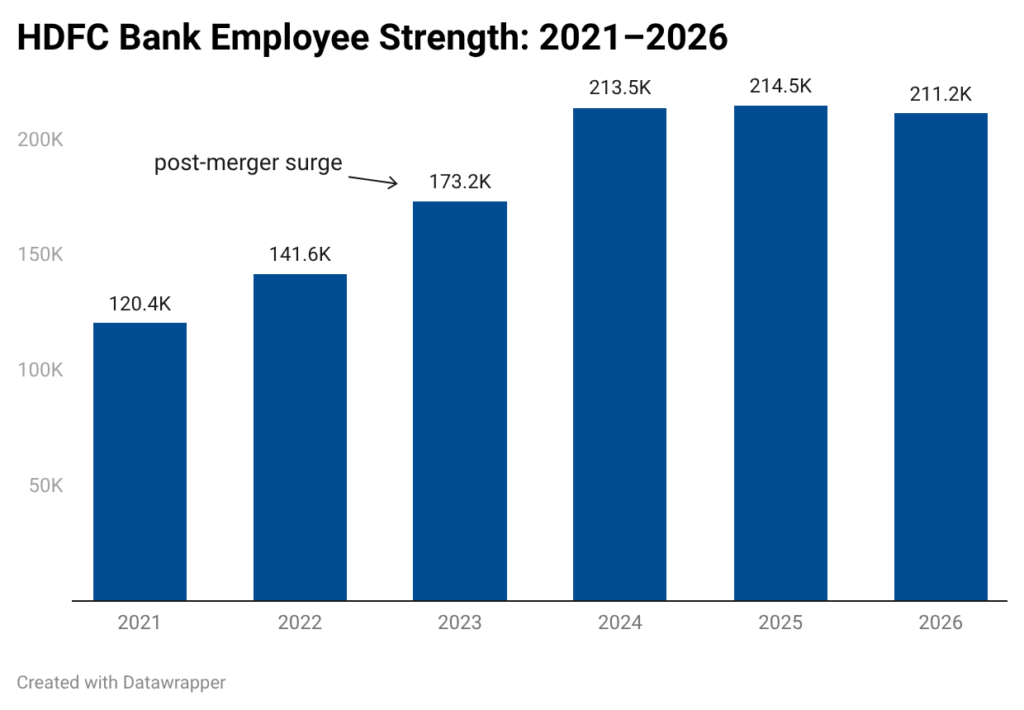
For years, HDFC Bank was the benchmark every Indian private bank aspired to match. Renowned for its disciplined lending, strong asset quality and consistent profitability, it spent more than two decades setting the standard for banking excellence. Today, the conversation around HDFC Bank has changed. While it remains India’s largest private sector bank with assets exceeding ₹49 lakh crore, more than 120 million customers, and one of the country’s most extensive banking networks investors are now closely watching whether its biggest strategic bet, the 2023 merger with HDFC Ltd, can translate into stronger long-term growth despite short-term pressure on profitability.
Be the first to comment